
We bring your income and investments together into one tax-smart plan, built to give you a steady retirement paycheck.
Most of the people we work with are getting close to retirement or already there. Wherever you are, the goal is the same: a paycheck you can plan around.
The choices you make now about saving, taxes, and when to stop working shape the paycheck you'll live on. We build the plan while there's still time to adjust it.
Turning a lifetime of savings into income is a different job than building it. We map out where each month's paycheck comes from, when to claim Social Security, and how to handle the first years of withdrawals.
Maybe the plan you started with no longer fits, or nobody is watching the taxes. We review what you have, keep what works, and bring the rest into one coordinated plan.
You may not need a full retirement income plan yet. Your investments can still be professionally managed with the same disciplined approach we use for retirees, so the money you're saving today is working toward the day you'll need it.
A lower, management-only fee schedule is available.
Find your investment strategySome advisors only manage investments. Others only sell annuities and life insurance. Most retirements need both, working together under one plan.
Diversified, low-cost portfolios managed for you. Rebalanced on a schedule, tax-aware, and matched to your risk tolerance and capacity.
Annuities and life insurance, used only where they solve a specific problem: covering essential expenses for life, cushioning market drawdowns, or protecting the people you love.
The point is coordination. Your investments, annuities, and life insurance are chosen together, so each one has a clear role in your plan.
Your plan is built in four layers, from the bottom up. Each layer has one job, and each one is funded with the tool best suited to it.
Built from the bottom up. When your essential bills are covered by income that doesn't depend on the market, the money in your Growth Engine can stay invested through the drawdowns instead of being sold at the wrong time.
Every withdrawal has a tax cost. We plan which accounts you draw from and when, looking to lower what you pay over your lifetime, not just this year.
What you want to leave to family or causes you care about, positioned to pass on efficiently.
Funds your lifestyle spending, keeps pace with inflation, and is managed to ride out market swings.
Closes any gap between your Foundation and your essential expenses, so the bills are covered for life.
The income you already have coming. We help you claim it at the right time, because it pays you for as long as you live.
You'll always know where you are in the process and what comes next.

A short, no-cost conversation about where you are, where you want to go, and whether we're the right fit for each other.
We map your income sources against your expenses, test the plan against market drawdowns and inflation, and show you the paycheck it can support.
Accounts open in your name at Charles Schwab. Your investments go into the portfolio that fits you, and an annuity or life insurance is added only where it solves a problem in your plan.
Ongoing management, an annual review, and access to your advisor whenever you need it. When life or markets change, the plan changes with them.
Five low-cost building blocks, in four mixes: U.S. stocks, dividend stocks, international stocks, short-term Treasuries, and gold.
For steady income with the smallest swings.
More growth, with a large stability sleeve.
A middle path between growth and stability.
For longer time horizons and investors comfortable riding out drawdowns.
A short set of questions about your time horizon, your income needs, and how you react when markets move. Your answers point to the portfolio that fits you best.
It's a starting point for a conversation, not a final answer.
Take the assessment
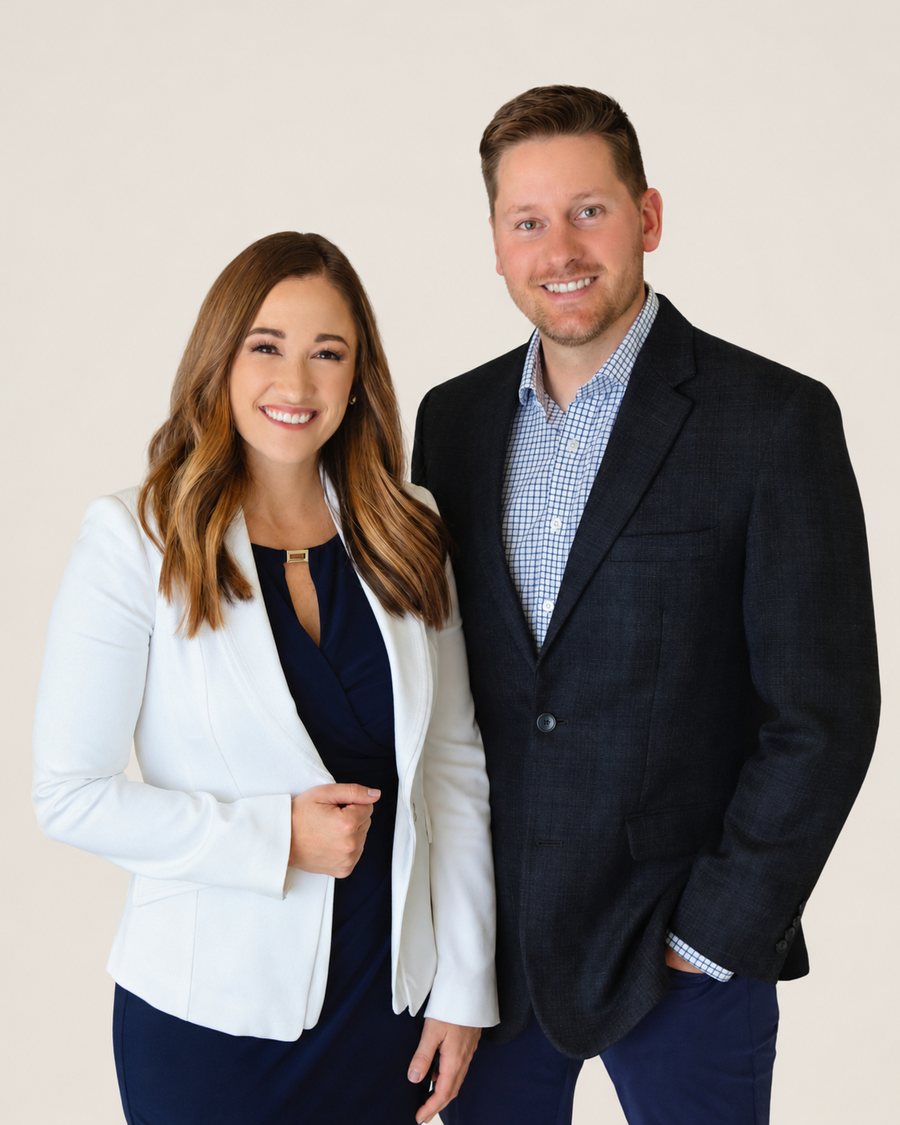
Sean and Megan Jantz are independent advisors held to the fiduciary standard, based in Twin Falls, Idaho. Together, they help families build, protect, and grow their wealth with confidence, with a focus on the years leading up to and through retirement.
Since 2012, Sean and Megan have guided families through every stage of the financial journey. Their work centers on retirement income, investment strategy, protection, and tax-smart planning, with every piece working together as one plan.
Their approach goes beyond traditional advising. They act as partners and coaches, simplifying complex ideas, building long-term relationships, and making sure clients feel supported at every step. They believe great planning is built on clear communication, straight-talk explanations, and the discipline to do the right thing.
A plan only works if you understand it.
Outside the office, Sean and Megan are raising their two daughters, Juliet and Jesslyn. They put family first, stay active in their community, and believe in the Idaho values of honesty, faith, and hard work.
No cost and no obligation. No question is too basic.
Schedule a conversationA short conversation is the fastest way to find out where you stand, and whether we're the right fit.
No cost. No obligation.